From market signals to financing strategies and upgrading decisions, explore curated learning to help you buy, sell, or invest with clarity and confidence.
From market signals to financing strategies and upgrading decisions, explore curated learning to help you buy, sell, or invest with clarity and confidence.
Recent Hot Topics Singaporeans Care About
How We Help You Learn
Our education ecosystem spans seminars, articles, market insights, tools, and data-driven frameworks to help every homeowner and investor make smarter decisions.
Start with our latest guides, insights, and explainers. Updated regularly to help you decode the Singapore property market.
Curated Content Just For You to Stay Ahead

Eight Tenants in One Flat: Is the Extra Rent Worth It?
TL;DR Eight tenants could mean more rental income, but does it actually mean more profit? Singapore's temporary occupancy relaxation allows eligible HDB and private residential properties to house up to eight unrelated persons until 31 December 2028, subject to the applicable conditions. The potential upside: Six tenants paying $700 each bring in $4,200 a month. Eight tenants paying $650 each would generate $5,200, an extra $1,000 monthly or $12,000 annually before additional costs. More tenants, more expenses: Higher utility bills, maintenance, cleaning, wear and tear, and potential tenant disputes can eat into the additional rental income. Know the occupancy rules: The relaxed cap applies to 4-room and larger HDB flats and private homes of at least 90 sqm. HDB owners need approval, while eligible private-home owners must register with URA. For HDB bedroom rentals, the eight-person limit includes owners and authorised occupiers. Don't overlook vacancy risk: A more crowded home may be less attractive to some tenants. If filling rooms takes longer or tenants move out more frequently, the additional rental income could quickly shrink. The higher cap is temporary: The relaxation currently ends on 31 December 2028. Landlords should ensure their rental strategy remains financially viable even if the occupancy limit returns to six. Bottom line: Just because you can accommodate eight tenants doesn't mean you should. What matters is how much additional income remains after expenses, vacancy and management costs. Aim for sustainable rental returns, not simply the highest possible tenant count. Your 4-room HDB flat is already rented out to six unrelated tenants. Under the temporary occupancy relaxation, you could, subject to HDB approval, add two more until 31 December 2028. Do you take the extra rent, or keep the flat less crowded?That is the practical question behind the extension announced by HDB and URA.The relaxed cap applies to 4-room and larger HDB flats and private residential properties of at least 90 sqm in strata or lot area. Eligible private-home owners must register with URA to use the higher cap.However, there are other conditions for HDB owners. For a whole-flat rental, a 4-room or larger flat can have up to eight tenants under the temporary relaxation. If you rent out bedrooms while continuing to live there, the eight-person cap includes the owners and authorised occupiers as well as the tenants.But should you restructure your rental to fit eight tenants, and would that be the most profitable strategy? In this article, we will explore: On paper, two extra tenants add $1,000 a month Eight tenants sounds good, until... Some things to know before you take on those extra tenants Eight is a ceiling, not a target On paper, two extra tenants add $1,000 a monthTake a whole-flat 4-room HDB rental with six unrelated tenants paying $700 each. Gross rent is $4,200 a month.If you add two tenants and reduce the rent to $650 per person because the home is more crowded, gross monthly rent becomes $5,200.Under those assumptions, the uplift is $1,000 a month, or $12,000 a year. That's before any additional utilities, cleaning, maintenance, vacancy or reletting costs.For an owner with a mortgage to service, that extra $1,000 a month could make a meaningful difference to the property's cash flow.This is probably why the extension caught some landlords' attention in the first place. Why not make use of the relaxed policy and earn more from the same property? Enjoying our insights so far? Stay updated with the latest property trends, expert analysis, and market perspectives from PropNex. Join our mailing list Eight tenants sounds good, until...But as good as it sounds to earn two more rental payments, you need to remember that you are also adding two more people to the household.That means two more people using the bathrooms. Two more people using the kitchen. Two more people using the washing machine, air-conditioning and common spaces. More wear and tear. More cleaning. More chances of something breaking.Not to mention, 8 people sharing a small space could easily create tension in the house.Someone may complain that the living room is always occupied. Or a certain tenant keeps leaving a mess in the kitchen. Meanwhile, a different tenant always has friends over. And everyone can't agree on the air-con settings.These things sound trivial until you, the landlord, are receiving all their complaints via WhatsApp.Crowding can also narrow your tenant pool. If a comparable room in a less crowded home costs only a little more, some tenants may prefer the extra space and privacy.That does not mean eight occupants will automatically lead to higher turnover. But any additional vacancy or reletting cost will eat into the $1,000 monthly gross-rent uplift.That extra $12,000 is therefore not additional profit. Here is a more realistic formula to calculate your net benefit:projected rent at eight occupants ? current rent at six ? additional running and maintenance costs ? expected vacancy and reletting costs.Now after all the deduction, is the remaining margin still worth the additional management?In any case, the higher occupancy cap offers flexibility, but it's not necessarily better to have more tenants.Some things to know before you take on those extra tenantsThe rules differ between whole-flat and bedroom rentals. For a 4-room or larger HDB flat rented out in full, the temporary limit is eight tenants. For bedroom rental, the maximum is eight occupants in total, including the owners and authorised occupiers, and the owners must continue living in the flat. A 4-room or larger flat may rent out up to two bedrooms. HDB approval is required before the tenancy begins.For a private residential property of at least 90 sqm, the owner must register the property with URA to qualify for the higher cap of eight unrelated persons. Without that registration, the usual cap of six applies.Eight is a ceiling, not a targetThe decision becomes clearer once you stop treating eight occupants as the objective. Add the seventh and eighth tenants only if they still improve net cash flow after any rent discount, higher running costs, vacancy risk and the additional management burden.And run the property on a six-person fallback. Under the current rules, the higher cap ends on 31 December 2028 unless it is extended again, so landlords should not build a longer-term rental plan that only works at full eight-person occupancy.The number to optimise is not headcount. It is sustainable cash flow. Views expressed in this article belong to the writer(s) and do not reflect PropNex's position. No part of this content may be reproduced, distributed, transmitted, displayed, published, or broadcast in any form or by any means without the prior written consent of PropNex. For permission to use, reproduce, or distribute any content, please contact the Corporate Communications department. PropNex reserves the right to modify or update this disclaimer at any time without prior notice.
Read More
Well-Located Executive Condominium Project Coming To Canberra Drive
Executive condominium (EC) sites are not always located close to an MRT station. This is what makes the upcoming EC in Canberra Drive one to note. The project which can yield 185 new EC units is minutes' walk to the Canberra MRT station and within easy reach of schools and daily amenities. In a land tender that closed on 1 October 2026, the Canberra Drive EC site attracted 13 bids with the top bid of $163.9 million from a tie-up that includes Santarli Realty, Heeton Holdings, and Kay Lim Realty - which works out to a land rate of $825 psf per plot ratio (psf ppr).The site also happens to be the first EC plot to be launched for tender since the new EC measures were announced on 8 May 2026, which made it one of the more closely watched GLS parcels. Under the new EC rules, the minimum occupation period (MOP) has been extended to 10 years from 5 years, the deferred payment scheme will be removed, and there is greater priority given to first-timer buyers. Are ECs still an attractive option?With the terms of ownership changing, prospective buyers may be asking whether an EC remains an attractive option for their next home. Generally, ECs remain an appealing option for buyers who are comfortable with the longer ownership commitment.ECs offer the opportunity to own a condominium-style home with private facilities, while potentially offering a more accessible entry point than a comparable new private condo. For eligible buyers, this can provide a pathway to private homeownership, particularly for households looking to upgrade from an HDB flat.For first-timers, the new rules are broadly in their favour. There is far less competition from second-timers during the early sales period, and the 90% quota over a two-year priority window will give households more time to sort out financing without being rushed into a launch-weekend purchase decision.The revised 10-year MOP means EC buyers will need to take a longer-term view of their homeownership journey, making the location and attributes of the EC all the more important. In this regard, Canberra Drive EC's site offers several factors for prospective buyers to consider.Connectivity and convenienceCanberra MRT station on the North-South Line is within walking distance, giving residents a direct rail link towards Yishun, Ang Mo Kio, Toa Payoh, Orchard and the city centre, as well as northwards to Woodlands, which is an interchange with the Thomson-East Coast Line.The plot sits next to Jalan Sendudok Park, and the Bukit Canberra integrated hub - where the hawker centre, polyclinic, and swimming complex are located - is also a short walk away. Meanwhile, more retail and F&B offerings can be found at Canberra Plaza, Sembawang Shopping Centre and Sun Plaza.School proximityThe availability of schools in the Sembawang and Canberra neighbourhood adds to the project's appeal for families. There are two schools within 1km from the Canberra Drive EC site, being Sembawang Primary School and Wellington Primary School.In the 1-2km range, more primary school options open up, including Canberra Primary School, Endeavour Primary School, Ahmad Ibrahim Primary School, and Yishun Primary School, amongst others.Long-term transformation: Sembawang ShipyardBeyond the immediate neighbourhood, the planned redevelopment of Sembawang Shipyard nearby provides a longer-term development story for the locale.The shipyard area is expected to be progressively transformed into a mixed-use waterfront destination, with a combination of housing, amenities and recreational offerings. If implemented as planned, the redevelopment could introduce a new dimension to Sembawang's identity and enliven the entire area.For residents of Canberra Drive EC, the potential benefits could include greater access to waterfront spaces, additional lifestyle amenities and a broader mix of recreational and community offerings.Why Canberra Drive EC might see positive interest?Apart from the strong location attributes, the Canberra Drive EC also falls on the right side of a recent policy change. At the National Day Rally on 23 August 2026, the Government announced that the EC household income ceiling would be raised from $16,000 to $18,000 a month. It applies only to EC sites with tenders closing on or after 24 August 2026.The higher income ceiling widens the pool of eligible households who are able to purchase new ECs, and could give buyers more room on financing. About the developersA subsidiary of the home-grown Santarli Group established since 1983, Santarli Realty has undertaken a range of building projects from institutional to industrial, carrying out engineering works in both the private and public sectors. Some residential projects in their portfolio include Executive Condominiums Tenet and Altura, boutique projects like Sanctuary @ Newton, and the DBSS project Adora Green. Heeton Holdings is a Singapore-based company listed on SGX with a focus on property development, investment and management. Their global portfolio extends across Thailand, Australia, Japan, Malaysia, Vietnam and The United Kingdom, and comprises of residential, commercial properties and hotels. Past projects include Sun Plaza shopping mall, and boutique residential projects like DLV at Dalvey Road and The Element at Stevens Road. Kay Lim Realty is a subsidiary of the Singapore construction group Kay Lim Holdings, with 33 years of experience in construction and a solid track record in property development since 2010. Their residential portfolio includes the DBSS project Pasir Ris One, Executive Condominiums like The Vales and CityLife @ Tampines, and boutique condominium projects like Rangoon 88 and Sanctuary @ Newton.
Read More
Stop Treating CPF's 4% as a Fixed Rate
TL;DR CPF's 4% interest floor is attractive, but it is not guaranteed forever. With the current extension ending on 31 December 2027, the bigger question is whether locking away more money for retirement still makes sense if the floor rate is lower in future. 4% is a floor, not the default rate: SMRA savings earn the higher of the pegged rate, based on Singapore Government Securities yields plus 1 percentage point, or the Government's minimum floor rate. For 4Q2026, the computed rate is 3.06%, below the current 4% floor. The floor could change: Unlike the OA's legislated 2.5% minimum, the SMRA's 4% floor is a Government policy that has been extended periodically. If it is not renewed in future, your savings would still earn interest, but potentially at a lower rate. Top-ups are irreversible: Cash top-ups and CPF transfers under the Retirement Sum Topping-Up Scheme cannot simply be withdrawn later if interest rates change or your financial needs shift. Keep your options open: Build your emergency fund first, then consider how much you can comfortably set aside for retirement without compromising your need for accessible cash. Top up based on your retirement goals: Use the Full Retirement Sum (FRS) and Enhanced Retirement Sum (ERS) as reference points. Consider your desired retirement payouts, available funds and eligibility for tax relief on qualifying cash top-ups, rather than rushing to lock in 4%. Bottom line: The decision is not just about earning 4%. It is about whether you are comfortable giving up liquidity in exchange for long-term retirement savings growth, even if the interest floor is lower one day. If you may need the money for a home upgrade, right-sizing move or other major expenses, weigh those plans together before topping up. On 22 September 2026, the government confirmed that our Special, MediSave and Retirement Account (SMRA) savings will keep earning at least 4% a year until the end of 2027.But should you really be planning your finances assuming that 4% will last forever? In this article, we will explore: The 4% is a floor, not the formula What if the floor rate "safety net" is removed one day? So how much should you actually lock away? Before you top up, pressure-test the trade-off Final thoughts The 4% is a floor, not the formulaYour SMRA actually doesn't earn a flat 4% by default. It earns whichever is higher between a pegged rate or a floor rate.The pegged rate is calculated based on the 12-month average yield of 10-year Singapore Government Securities, plus 1 percentage point, recalculated every quarter. When bond yields are strong, this formula can push your SMRA interest rate above 4%. But when yields are weak, like they've been for most of the past two years, the formula falls short.For October to December 2026, the computed SMRA rate is 3.06%, based on the average yield of 10-year Singapore Government Securities from August 2025 to July 2026.What if the floor rate "safety net" is removed one day?The difference is that the OA's 2.5% minimum is legislated. Meanwhile, the SMRA's 4% floor is a Government policy that has been extended periodically, with the current extension running only until 31 December 2027.But to be fair, their track record is excellent. The 4% floor rate has been repeatedly extended since it started in 2008 (usually announced sometime in September, for the year ahead).Regardless, "renewed every year so far" does not mean "guaranteed forever". So what happens if, in some future year, the renewal doesn't come through?Your SA and RA won't suddenly earn nothing, don't worry. They'd likely drop to something close to that formula rate, maybe low 3% territory based on where things stand today. Still safe, just less generous than what you've gotten used to.But, you need to remember that any money you put into your SA or RA through the Retirement Sum Topping-Up Scheme (RSTU), whether cash or a CPF transfer, is irreversible.So, unlike savings or investments that can be reallocated, you can't simply withdraw those RSTU top-up monies and put it somewhere better. In that case, you could be earning less on cash you already can't touch until payout, with no way to undo the decision.Something that seems like a mild inconvenience at first may be something worth thinking through before you make your top-ups. Enjoying our insights so far? Stay updated with the latest property trends, expert analysis, and market perspectives from PropNex. Join our mailing list So how much should you actually lock away?Honestly, there's no single right answer here, everyone's situation is different. But you can use the calculator below to compare what your top-up could grow into if the floor holds at 4%, versus if it eases. Top-up amount$0 Years until you start CPF LIFE payouts0 years Comparison rate, if the floor isn't renewed0.00% If floor holds at 4%$0 If it settles at 0.00%$0 The gap$0 Disclaimer: Illustrative purposes only. Not a projection of your actual CPF balance. This calculator assumes the rate you pick stays constant for the full period and ignores annual contributions, extra interest tiers, and CPF LIFE payout mechanics. All amounts in SGD. This calculator needs JavaScript enabled to update its results. (() => { const money = new Intl.NumberFormat('en-SG', { style: 'currency', currency: 'SGD', currencyDisplay: 'narrowSymbol', minimumFractionDigits: 0, maximumFractionDigits: 0 }); document.querySelectorAll('.cpf-topup').forEach(root => { if (root.dataset.initialized) return; root.dataset.initialized = 'true'; const inputs = Object.fromEntries(['amount', 'years', 'rate'].map(key => [key, root.querySelector('[data-input="' + key + '"]')] )); const setValue = (key, text) => { root.querySelector('[data-value="' + key + '"]').textContent = text; }; const setResult = (key, value) => { root.querySelector('[data-result="' + key + '"]').textContent = money.format(value); }; function update() { const amount = Number(inputs.amount.value); const years = Number(inputs.years.value); const rate = Number(inputs.rate.value); const floorBalance = amount * Math.pow(1.04, years); const comparisonBalance = amount * Math.pow(1 + rate / 100, years); setValue('amount', money.format(amount)); setValue('years', years + (years === 1 ? ' year' : ' years')); setValue('rate', rate.toFixed(2) + '%'); setValue('comparison', rate.toFixed(2) + '%'); setResult('floor', floorBalance); setResult('comparison', comparisonBalance); setResult('gap', floorBalance - comparisonBalance); Object.entries(inputs).forEach(([key, input]) => { input.style.setProperty('--fill', ((Number(input.value) - Number(input.min)) / (Number(input.max) - Number(input.min)) * 100) + '%'); input.setAttribute('aria-valuetext', key === 'amount' ? money.format(amount) + ' Singapore dollars' : key === 'years' ? years + ' years' : rate.toFixed(2) + ' percent'); }); } Object.values(inputs).forEach(input => input.addEventListener('input', update)); update(); }); })(); Even in the more cautious scenario, your money is still compounding safely inside CPF. That gap is real over 20 or 30 years, no doubt. Just make sure you're okay not touching this money for the rest of your working life, whichever rate ends up applying.Before you top up, pressure-test the trade-off:Your emergency fund comes first.CPF top-ups are irreversible, so don't move money you may need for unexpected expenses into your SA or RA. That 4% interest may sound attractive, but it doesn't replace having cash you can access when you need it. Use the FRS and ERS as reference points, not the default target.The amount you can top up depends partly on your age. If you're below 55, cash top-ups to your SA are generally capped by the prevailing Full Retirement Sum (FRS). From 55, you can top up your RA up to the prevailing Enhanced Retirement Sum (ERS).How far you go is ultimately a personal decision. Consider the monthly retirement payout you want, how much you can comfortably set aside, and how much liquidity you're willing to give up. Don't rush topping up just to lock in 4%.There's no need to rush a CPF transfer because you're worried about missing out on the 4% floor. The more important question is whether putting more money into CPF makes sense for your own circumstances.If you're making a qualifying cash top-up, you may also be eligible for tax relief, subject to the applicable rules and annual limits. Transfers between your CPF accounts do not qualify for this tax relief.Final thoughtsThe more useful question is not whether 4% looks attractive today. It is whether your retirement plan still works if that floor is lower one day, and whether you are comfortable giving up liquidity in exchange for long-term compounding.If the same pool of money may also matter for an upgrade, right-sizing move or another retirement decision, model those choices together before locking it away. Views expressed in this article belong to the writer(s) and do not reflect PropNex's position. No part of this content may be reproduced, distributed, transmitted, displayed, published, or broadcast in any form or by any means without the prior written consent of PropNex. For permission to use, reproduce, or distribute any content, please contact the Corporate Communications department. PropNex reserves the right to modify or update this disclaimer at any time without prior notice.
Read More
HDB Prices Have Fallen Twice. Will Your Older Flat Rebound?
TL;DR HDB resale prices have fallen for two consecutive quarters, but that does not mean older-flat owners should rush to sell. The bigger question is whether waiting for a rebound still works when your flat's remaining lease, future buyer pool and your own retirement timeline are changing at the same time. The overall HDB market is not your individual flat: Million-dollar transactions can coexist with a softer resale index because location, remaining lease, size, amenities and buyer demand differ substantially from one flat to another. A shorter lease can change who can comfortably buy your home: As the remaining lease falls, CPF usage and financing considerations may become more important for future buyers, potentially affecting your flat's marketability. Your neighbour's sale is not your price floor: A price achieved two years ago reflects another unit and another market. What matters is what buyers are paying for genuinely comparable flats today. Waiting is itself a property decision: Holding for another five or ten years means accepting changes to your remaining lease, retirement timeline, housing needs and potential future buyer pool while hoping the market moves in your favour. Pressure-test the price you are waiting for: If your retirement or right-sizing plan depends on eventually selling at a particular price, ask whether the plan still works if the market never gives you that number. Bottom line: Do not simply ask whether HDB prices will rebound. Ask whether keeping your particular flat for another five or ten years still helps you get where you want to be. Your exit strategy should already be part of the decision to keep holding today. Your neighbour sold their HDB flat for $600,000 two years ago.Your flat is in the same block, with a similar layout. So when a buyer offers you $570,000 today, you may naturally wonder:Why should I accept $30,000 less?Perhaps it makes more sense to wait.After all, HDB resale prices have risen considerably over the years. Million-dollar flats are still making headlines. And if the market eventually picks up again, perhaps you could get closer to the price you have in mind.For many long-time homeowners, that thinking is understandable.But there is another question worth asking:What if the HDB market rebounds, but your particular flat does not rebound at the same pace?That question has become more relevant after the HDB Resale Price Index recorded two consecutive quarterly declines in 2026, the first back-to-back fall in around seven years.AT A GLANCEThe recent fall in HDB resale prices is small and does not mean homeowners need to rush to sell. But for owners of older flats, waiting for a market rebound comes with another consideration: as the remaining lease shortens, financing, CPF usage and the profile of future buyers can change too. In this article, we will explore: HDB Prices Have Fallen Twice. Is This Just A Blip? If Prices Are Falling, Why Are Million-Dollar Flats Still Making Headlines? Meet Mr Tan: Should He Take $570,000 Or Wait For $600,000? As The Lease Shortens, It Is Not Just The Seller Who Has To Think Differently Your Neighbour's $600,000 Sale Is Not Your Price Floor Does This Mean Owners Of Older Flats Should Sell Now? Waiting Is Not Doing Nothing Before You Wait For The Rebound, Pressure-Test These Five Things Don't Just Wait For "The HDB Market" To Recover HDB Prices Have Fallen Twice. Is This Just A Blip? HDB's latest resale statistics show that the Resale Price Index declined by 0.1% in Q1 2026, followed by a further 0.3% decline in Q2.In isolation, those numbers are hardly dramatic.A cumulative fall of roughly 0.4% does not constitute a market crash, especially after years of price growth.HDB's data also show that resale prices in Q1 2026 were still 1.2% higher year-on-year. Meanwhile, 6,396 resale flats changed hands in Q2, 1.8% more than in the previous quarter, although transaction volume was 9.9% lower than a year earlier.So the picture is not one of a market suddenly falling apart.It is one of momentum cooling.For an owner who has no plans to move, this may not matter very much.But for someone approaching retirement, thinking about right-sizing or expecting to unlock a certain amount from their flat within the next few years, a change in market momentum deserves closer attention.Especially if the plan is simply:"I'll wait until the price comes back."If Prices Are Falling, Why Are Million-Dollar Flats Still Making Headlines? This is where the HDB resale market can seem contradictory.The overall resale index has fallen for two quarters.Yet exceptional HDB flats continue to transact at seven-figure prices.Both things can happen at the same time because there is no single type of HDB resale flat.A relatively new, large flat in a sought-after location near transport, established schools and amenities may attract a very different pool of buyers from an ordinary flat with a much shorter remaining lease.Consider some of the factors that can differentiate two HDB flats: Factor Flat A Flat B Remaining lease Longer Shorter Location Highly sought-after More conventional Size/layout Larger or relatively scarce More readily available Nearby amenities Strong connectivity and established amenities Varies Buyer financing considerations Generally less affected by lease age Can become more important as lease shortens Potential buyer pool May remain broad Can change over time That does not mean a newer flat will always outperform an older one.An older flat in an excellent location can still attract substantial demand. Conversely, age alone does not determine whether a property will sell well.There is also no official HDB sub-index showing that all older flats are currently falling faster than newer ones, so it would be misleading to make that claim.The more useful takeaway is simpler:A record transaction elsewhere in the HDB market may tell you very little about what buyers will pay for your specific home.Meet Mr Tan: Should He Take $570,000 Or Wait For $600,000? Consider a hypothetical homeowner.Mr Tan is 61.His HDB flat has approximately 55 years of lease remaining. A neighbour sold a comparable unit for $600,000 during a stronger market two years ago.Today, Mr Tan thinks he could sell for around $570,000.He is considering right-sizing when he reaches 70, so his instinct is to wait.Why lock in $570,000 now if another upswing could eventually bring the price back towards $600,000?There is nothing inherently wrong with that decision.But here is what Mr Tan needs to recognise.If he waits another nine years, he will not be trying to sell exactly the same asset that he owns today.His flat would then have roughly 46 years of lease remaining.The market could be higher.It could be lower.But regardless of what happens to the HDB index, one thing will definitely have changed: the remaining lease.And that can affect the calculations of the person on the other side of the transaction.As The Lease Shortens, It Is Not Just The Seller Who Has To Think Differently When homeowners think about lease decay, the conversation often becomes:"Will my flat lose value?"That may be too simplistic.A more useful question is:"How easy will my future buyer find it to purchase this flat?"That is where CPF usage and financing become relevant.Under current CPF Board rules, the amount of CPF Ordinary Account savings a buyer can use depends partly on the property's remaining lease.Where the property can cover the youngest buyer until at least age 95, CPF usage can generally be made up to the applicable housing limits. Where the lease does not cover the youngest buyer until age 95, CPF usage may be pro-rated, provided the property has at least 20 years of remaining lease.Under HDB's current housing-loan rules, a resale flat may qualify for a maximum Loan-to-Value limit of up to 75% of the lower of the resale price or valuation if its remaining lease covers the youngest applicant until at least age 95. Otherwise, the maximum LTV limit is pro-rated.Financial institutions may also impose restrictions when financing flats with shorter remaining leases.This does not mean an older flat suddenly becomes impossible to buy.It means the financing equation can gradually become more important.The Same Flat Can Look Different To Two BuyersReturn to Mr Tan's hypothetical flat nine years from now.Suppose it has approximately 46 years of lease remaining.A buyer aged 50 would see that lease lasting to around age 96.A buyer aged 35 would see it lasting only to around age 81.Under current CPF board rules, that distinction matters: whether the remaining lease covers the youngest buyer until age 95. Exact CPF usage would depend on the buyers' circumstances and should be calculated using CPF Board's housing usage calculator.Nothing about the physical flat has suddenly changed.The bedrooms are still there.The MRT station has not moved.The neighbourhood may be just as convenient, if not more.But the financial profile of the buyer who can purchase it comfortably may have changed.That is why the ageing of a flat is not simply about depreciation.It can also become a question of future marketability. Enjoying our insights so far? Stay updated with the latest property trends, expert analysis, and market perspectives from PropNex. Join our mailing list Your Neighbour's $600,000 Sale Is Not Your Price Floor This brings us back to perhaps the most difficult part of selling a home: separating today's market from yesterday's price.If Mr Tan's neighbour achieved $600,000, then receiving $570,000 can psychologically feel like losing $30,000.But Mr Tan never actually owned that extra $30,000.It was the price achieved by another seller, for another unit, at another point in the market.Today's buyer is not comparing Mr Tan's asking price against his neighbour's 2024 transaction alone.The buyer may also be looking at other HDB flats, newer estates, different locations or even other housing types within their budget.So rather than asking:"What was the highest price someone here managed to achieve?"a more useful question is:"What are buyers paying for genuinely comparable flats now?"That means looking at factors such as remaining lease, floor level, orientation, condition, location and recent transactions, rather than treating one record sale as the permanent benchmark for an entire block.Does This Mean Owners Of Older Flats Should Sell Now? No.Two quarters of modest price declines are not a reason for every older homeowner to rush onto the market.Holding can make perfectly good sense.If the home still suits your lifestyle, your housing costs are manageable and you have no need to access the property's value in the near future, there may be little reason to make a move solely because an index fell for two quarters.The market may strengthen again.Interest rates could change.Housing policies could evolve.Supply and demand could shift.And after years of gains, the recent price movement remains relatively small. This is a change in momentum, not evidence of a collapse.The more important distinction is why you are choosing to hold.Compare these two thoughts:"This home still suits me. I am comfortable staying here for another decade, regardless of short-term prices."versus:"I will not sell until somebody gives me the price my neighbour received."Both result in the same immediate action: keeping the flat.But they are very different decisions.The first is based on your housing needs and circumstances.The second depends on the market eventually delivering a particular number.Waiting Is Not Doing Nothing Selling feels like a decision.Waiting often does not.Yet for someone like Mr Tan, waiting another nine years is itself a property decision.During those nine years, several things happen simultaneously.His remaining lease shortens.His retirement gets closer.His own housing needs may change.The type of household most likely to buy his property may change.And the eventual amount he receives could influence what he can afford to do next.That does not make waiting bad.If the market appreciates strongly, Mr Tan could benefit.But it does mean he should understand what he is choosing to wait for.If his retirement plan only works if his flat eventually sells for $600,000, then the important question is not:"Can I wait until someone pays me $600,000?"It is:"What happens to my plan if they don't?"That small change in question turns a price expectation into a property strategy.Before You Wait For The Rebound, Pressure-Test These Five Things Rather than trying to predict whether HDB prices will rise or fall next year, an older homeowner can examine the factors they have more control over. Pressure-Test(TM) Question To Ask Yourself Your flat How much lease remains today, and how much will be left when you realistically intend to sell? Your market What are genuinely comparable flats selling for today, rather than simply the highest transaction nearby? Your future buyer Who is likely to buy your flat five or ten years from now, and could the remaining lease affect their financing or CPF usage? Your timeline Are you holding because the home still suits you, or mainly because you are waiting for a particular price? Your next move If your eventual sale proceeds are lower than expected, can your retirement, right-sizing or next-property plan still work? None of these questions tells you automatically to sell.They do something more useful.They tell you what needs to be true for holding to continue making sense.Don't Just Wait For "The HDB Market" To Recover The HDB resale market may rise again.It may remain relatively flat.Individual neighbourhoods and flat types may also behave differently from the overall index.But an index is ultimately an average.Your property is not.It has a specific remaining lease, location, floor, layout, condition, buyer pool and role within your wider financial plans.So for an owner approaching retirement, perhaps the most useful question is no longer:"Will HDB prices rebound?"It is:"If I keep this flat for another five or ten years, does it still help me get to where I want to be?"For some homeowners, the answer will be yes.Staying put may provide security, familiarity and a home they genuinely want to continue living in.For others, the exercise may reveal that too much of the next stage of their plan depends on a future selling price they cannot control.Either way, that is a much stronger basis for deciding than waiting for a neighbour's record price to come around again.Because your exit strategy should not begin only on the day you finally decide to sell.It should already be part of the decision to keep holding today. Views expressed in this article belong to the writer(s) and do not reflect PropNex's position. No part of this content may be reproduced, distributed, transmitted, displayed, published, or broadcast in any form or by any means without the prior written consent of PropNex. For permission to use, reproduce, or distribute any content, please contact the Corporate Communications department. PropNex reserves the right to modify or update this disclaimer at any time without prior notice.
Read More
You Bought A Condo To Rent Out? So Did Everyone Else
TL;DR The rental market is still growing, but that does not mean every new condo will rent easily at the price you want. For owners collecting their keys now, the bigger issue may be how many similar units are competing for the same tenants. Rental demand is still holding up: Private residential rents rose 0.7% in 2Q2026 after increasing 0.3% in 1Q2026. But more completed units and a 6.4% vacancy rate mean tenants have more choice. Your real competition is local: A new project can have many similar units entering the rental market at the same time. Tenants are comparing what is available today, not what you paid for your unit or what your neighbour achieved two years ago. Lower mortgage rates are not the whole story: Cheaper financing can improve monthly cash flow, but a lower achievable rent or longer vacancy can easily offset those savings. Watch the cost of waiting: Holding out for an extra $300 a month may sound reasonable, but one month of vacancy at $3,800 would take more than a year of that higher rent to recover. Look at the actual return: Gross rent is only the starting point. Mortgage interest, maintenance fees, property tax, repairs and vacancy periods all affect what you actually make from the property. Bottom line: Buying a condo for rental income is not simply a question of whether rents are rising. The more important question is whether your particular unit still works at today's achievable rent, costs and level of competition, even if it takes longer to find a tenant. After years of waiting for construction to finish, your new condo is ready. Now all you have to do is find a tenant so you can collect rent and use that income to offset your mortgage.There is just one small problem: you may be collecting your keys at the same time as many other owners in your project or nearby developments. That can mean several similar units competing for the same tenants, even if the wider rental market is still holding up. So, what does this mean for you? In this article, we will explore: Rents are recovering, but your competition may still be local Your tenant does not care what you paid The mortgage may be cheaper but how about your rental yield? What do you do when the offers are lower than expected? Asking the real questions So, is buying a condo for rental income a bad idea? Rents are recovering, but your competition may still be localSingapore's private rental market had just gone through one of its strongest runs in years. In 2022, rents for non-landed private homes rose by almost 30% over the year. Even in 2023, when rental growth started to cool, non-landed rents still increased by 6.9%.So if you bought a new launch between 2021 and 2023, you might have thought "by the time my unit is completed, there should be plenty of tenants willing to pay". And yet, landlords are experiencing a different reality today.To be clear, Singapore's rental market has not suddenly collapsed. URA's Q2 2026 data shows that private residential rents increased by 0.7% quarter-on-quarter, up from the 0.3% increase recorded in Q1.So it's not that no one wants to rent. There are still plenty of tenants out there. But the rental market you are entering today is not the same one you were looking at when you bought.There is more supply now. About 21,300 private residential units, including ECs, were completed in 2023, more than twice the number completed in 2022 and the highest annual completion level since 2016, according to URA.And there is more on the way. According to URA, 1,611 private residential units and 872 EC units obtained TOP in the first half of 2026 alone. And that's not even the major completion wave. URA also stated in its Q2 2026 release that around 60,600 private residential units, including ECs, are expected to be completed in the coming years. Of these, about 25,900 are expected to be completed by 2028.Yet, the vacancy rate for completed private residential units edged up from 6.2% in Q1 to 6.4% in Q2.For owners, especially those in newly completed projects, the pressure is on. Several similar units may be marketed for rent at the same time, giving tenants more choice and putting pressure on asking rents, even though the broader rental index is rising.Your tenant does not care what you paidIt's a hard pill to swallow, but it's true nevertheless.You may have bought your unit for $1.5 million. You may have taken a $1 million mortgage. You may have calculated your expected rental yield using the rent your neighbour was getting two years ago.Your tenant does not care. They are looking at what else they can rent today.If another condo nearby has a similar-sized unit with newer fittings, better facilities or a more attractive rate, that becomes your competition. Enjoying our insights so far? Stay updated with the latest property trends, expert analysis, and market perspectives from PropNex. Join our mailing list The mortgage may be cheaper but how about your rental yield?Mortgage rates are no longer at the highs that many buyers experienced in 2022 and 2023.Some current bank packages are priced off 3-month compounded SORA, with the final rate depending on the lender, package and borrower. Financing costs may be lower than the peaks seen in 2022 and 2023.That can certainly help monthly cash flow. But cheaper financing does not automatically make the investment more profitable, especially if the achievable rent or occupancy is weaker than expected.Suppose your mortgage payment falls by $300 a month after refinancing. If the rent you eventually secure is $300 lower than you expected, the benefit has effectively disappeared.And rental income was never the same thing as rental yield in the first place.Your rent has to be considered against the price you paid for the property, as well as interest, maintenance fees, property tax, vacancy periods, repairs and other costs.A unit renting for $4,000 a month may sound attractive. But if you paid $1.6 million for it, that is only $48,000 a year in gross rent, or a 3% gross rental yield before expenses. Once you account for the costs of owning the property, the net return is lower.What do you do when the offers are lower than expected?Let's say you've collected the keys, furnished the place and finally put it up for rent. You tell your agent you're hoping for $4,100.After some time, your agent calls to let you know they've found a tenant. But they're only offering $3,800, which is what similar units are charging.At this point, you might feel inclined to wait for a different tenant. Surely someone will come along who is willing to pay the asking price.However, if you leave the unit vacant for a month waiting for that extra $300, you've already forgone $3,800 in rent. At $300 more a month, you would need more than a year of higher rent just to make up for that one month of vacancy.Of course, this doesn't mean you should immediately take the first offer that comes along. If there are plenty of tenants looking for units like yours, holding out could make sense.The point is to look at the cost of waiting, not just the rent you want to get.Asking the real questionsIf you are holding a condo mainly for rental income, here are some questions you should ask yourself:What rent can I realistically get in the current market?Not what your neighbour got two years ago, or what you were hoping for when you bought. What are tenants actually willing to pay for a unit like yours now?How long could it take to find a tenant?A higher asking rent means little if the unit sits empty for weeks or months. Factor the potential vacancy into your calculations.What happens to my cash flow if the unit stays vacant for a month or two?Your mortgage, maintenance fees and other costs do not stop just because there is no tenant.What is my actual return after all the costs?Look beyond the monthly rent. Mortgage interest, maintenance fees, property tax, repairs and periods of vacancy all eat into your rental income.If rents stay flat for the next few years, does this property still make sense?If the answer is yes, you may have a property that still works for you even in a more competitive rental market.If the answer is no, it may be time to take a closer look at the assumptions behind your investment.So, is buying a condo for rental income a bad idea?Singapore's rental market is still holding up. URA's rental index rose 0.7% quarter-on-quarter in Q2 2026 after a 0.3% increase in Q1. So the issue is not that rental demand has collapsed. The more relevant question for landlords is whether their particular unit can secure a tenant quickly and at a rate that still makes sense.What has changed is the rental landscape you are stepping into.The pressure is likely to be uneven. A newly completed project can already have many similar units competing for tenants, while the broader supply pipeline becomes more significant through 2027 and 2028. That makes it risky to assume either that your unit will achieve the rent you once expected or that today's competition already represents the peak.Lower mortgage rates can help with your monthly cash flow, but they do not change that equation on their own. If your rent comes in lower than expected, or the unit sits vacant for a month or two, the difference can add up quickly.So perhaps the focus should not be on whether or not buying a condo for rental income is a bad idea. Rather, you should consider whether your property still works as a rental investment at today's rents, costs and level of competition.For owners collecting their keys in 2026, that may mean revisiting the assumptions they made when they bought. Views expressed in this article belong to the writer(s) and do not reflect PropNex's position. No part of this content may be reproduced, distributed, transmitted, displayed, published, or broadcast in any form or by any means without the prior written consent of PropNex. For permission to use, reproduce, or distribute any content, please contact the Corporate Communications department. PropNex reserves the right to modify or update this disclaimer at any time without prior notice.
Read More
Resale Landed Market Watch In August 2026
Tempered Resale Landed market activity in August In August, sales momentum in the landed home resale market took a pause due to the Hungry Ghost Festival which started in mid-August. Based on URA Realis caveat data, about 165 landed homes were transacted on the resale market in August 2026; with a combined transaction value came up to $1.03 billion - slightly lower compared to July (201 deals valued at $1.17 million). Upon an analysis of each transaction and their respective gains, most landed deals were profitable. There was a higher proportion of higher priced landed homes being sold compared with the previous month that came despite a slowdown in sales activity. Based on URA Realis caveat data, about 55.8% of resale landed homes sold in August were priced at $5 million and above, compared with about 47.3% in July. Meanwhile, 44.2% of the resale landed transactions were priced at below $5 million in August - declining from the 52.7% proportion in the previous month. Chart 1: Price range of private resale landed transactions in July 2026 vs August 2026Source: PropNex Research, URA Realis Overall landed home resale prices in August 2026 improved from the previous month, despite the decline in sales volumes. The overall landed homes resale prices grew by 4.1% month-on-month (MOM) to $2,031 psf; while prices were up by 10.3% compared to a year before. By property type, detached, semi-detached, terrace homes grew 5.7%, 15.3% and 1.5% MOM, respectively. By region, homes in the Rest of Central Region (RCR) and Outside Central Region (OCR) expanded by 8.7% and 0.6%, respectively. Meanwhile homes in the Core Central Region (CCR) bucked the upward trend, declining 5.4% (see table 1 below). Table 1: Average Unit Prices ($PSF) of Resale Landed Homes by monthSource: PropNex Research, URA Realis Resale landed homes performance by property type in August 2026 Table 2: Top 3 resale landed transactions by landed property type, in terms of estimated gains*Source: PropNex Research, URA Realis*Gains are derived from the resale transaction for each unit against the unit's last caveated transaction. The gains reflected is gross - it has not accounted for the applicable seller's stamp duties, interest payable, taxes and other relevant divestment costs. **Annualised gain is the compounded annual rate of return which shows the rate of return over the time period between the point of resale and the property's last caveated transaction, expressed in annual percentage terms. The formula for determining this is simply: [(current resale price) / (purchase price)] time period in years-1 Top landed transaction with highest gains (Detached) The top performing detached home transaction and overall landed transaction for the month was for a Good-class bungalow along Gentle Road in District 11 (Novena) that was sold for $18.5 million, up by $12 million from the last caveat lodged in June 2008 - this reflects an annualised profit of 6.0% after a holding period of 18 years. The GCB plot is situated within the Bukit Tunggal Good-class Bungalow (GCB) estate. Top landed transaction with highest gains (Semi-Detached) The best-performing semi-detached transaction was for the sale of a semi-detached property in Mount Sinai Avenue in Bukit Timah (District 10). It was sold for $10 million in August, with its last caveat being lodged in August 2005. The sale price is up by $8.2 million from the previous caveated price, representing an annualised gain of 8.6% per year for a holding period of over 20 years. The 999-year leasehold semi-detached house property is situated within walking distance to Dover MRT station. Top landed transaction with highest gains (Terrace House)The best-performing terrace home transaction was for a terrace house along Jupiter Road in the Bishan planning area (District 20). The freehold property is situated within Windsor Park landed estate and just a short distance away from Upper Thomson MRT station, and was sold for $7 million, reflecting an estimated gain of $5.8 million, representing an annualised gain of 6.9% per year from its last caveat lodged in October 1999, with a holding period of about 26 years If you are looking for high-end homes or good class bungalows in Singapore, contact PropNex's GCB and Prestige Landed department for buying and insights on the landed residential property market.For more property research insights, join PropNex Friends today. Disclaimer:While every reasonable care is taken to ensure the accuracy of information printed or presented here, no responsibility can be accepted for any loss or inconvenience caused by any error or omission. The ideas, suggestions, general principles, examples and other information presented here are for reference and educational purposes only.This information contained herein is not in any way intended to provide investment, regulatory or legal advice or recommendations to buy, sell or lease properties or any form of property investment. PropNex shall have no liability for any loss or expense whatsoever, relating to any decisions made by the audience.Views expressed in this article belong to the writer(s) and do not reflect PropNex's position.No part of this content July be reproduced, distributed, transmitted, displayed, published, or broadcast in any form or by any means without the prior written consent of PropNex.For permission to use, reproduce, or distribute any content, please contact the Corporate Communications department. PropNex reserves the right to modify or update this disclaimer at any time without prior notice.All copyrights reserved.
Read More
Resale Condo Market Watch in August 2026
Rebound in resale condo market activity in AugustSales momentum in the overall property market took a breather in August after a brief bounce back in July, including the resale condo market. About 932 condo units worth $1.85 billion was resold during the month - just slightly under the 1,033 resale transactions valued at $2.07 billion transacted in July. In August, resales transactions accounted for 83.1% of non-landed transactions, while new sale transactions accounted for 13.6% of transactions, as new sale activities paused during the month due to the Hungry Ghost Festival (see Chart 1).Chart 1: Proportion of private non-landed transactions (excl. EC) by sale type by monthSource: PropNex Research, URA Realis With the pause in new launch activity during the month, the average unit price of new non-landed homes dipped from the previous month. The average new sales price fell 3.1% month-on-month (MOM) to $2,612 psf in August, while the average resale unit price slipped by 0.5% MOM. As such, the new sale and resale price gap slipped from 48.8% in July (see Chart 2), from 43.5% in August. Chart 2: New sale and Resale Price gap of non-landed homes (overall) by monthSource: PropNex Research, URA Realis Modest gains amongst resale transactionsIn terms of profitability, resale condo units transacted in August saw larger gains compared with the previous month. Analysing the profits reaped by resale non-landed private homes in July 2026 and August 2026, it was found that resale condo deals in August garnered higher profits. That said, the proportion of loss-making transactions was also higher in August 2026 over the previous month. The resale profit analysis involves computing gains achieved for the units by matching the condo resale transactions in August against their respective previous purchase price, according to caveats lodged. The study showed that 17.0% of resale condo transactions (149 deals) in August made more than $1 million in profits, a bigger proportion compared with July (17.1%). Of these million-dollar profit-making deals, the deals was spread amongst the three market segments, 51.0% in the Core Central Region (CCR), 26.8% in the Rest of Central Region (RCR) and 22.1% in the Outside Central Region (OCR) . Loss-making deals in August accounted for 5.7% of transactions, higher compared with the proportion of loss-making deals (4.5%) in July (see Chart 3). Chart 3: Proportion of profit quantum of resale non-landed transactions (July 2026 vs August 2026)Source: PropNex Research, URA Realis The average profit was subsequently computed on a project basis. To minimise sampling errors, resale condominium projects that posted fewer than three transactions during the month are excluded from the study. Based on URA Realis caveat data analysed by PropNex Research, the most profitable condo for the month, was Jadescape, within District 20, which pulled in an average profit of more than $688,000 across five transactions in August. It was also the most profitable condo project in the RCR for the month.. Top Resale Condo projects^ in terms of average gross profit* (August 2026)Project NameNo. of transactionsAverage Profit Gained ($)Average Annualized Profit (%)#Year completedRegionJADESCAPE5$688,1804.42%2022RCRPARC ESTA9$562,4324.17%2022RCRAVENUE SOUTH RESIDENCE5$488,4531.83%2023RCRGRANDEUR PARK RESIDENCES6$432,4813.65%2020OCRTHE BAYSHORE5$423,4804.61%1997OCRNORMANTON PARK8$397,8133.23%2023RCRTREASURE AT TAMPINES7$396,8574.38%2023OCRPARK COLONIAL7$389,2863.58%2021RCRWHISTLER GRAND6$381,2673.68%2022OCRSTIRLING RESIDENCES6$358,6483.51%2022RCRSource: PropNex Research, URA Realis^projects with fewer than 5 transactions in the month are excluded from this analysis*Gains are derived from the resale transaction for each unit against the unit's last caveated transaction; the average profit is determined on the profits of all resale transactions in the development which occurred during the month. The profit reflected is gross - it has not accounted for the applicable seller's stamp duties, interest payable, taxes and other relevant divestment costs.#Annualised Gains is the compounded annual rate of return which shows the rate of return over the time period between the point of resale and the property's last caveated transaction, expressed in annual percentage terms. The formula for determining this is simply: [(current resale price) / (purchase price)] time period in years-1Analysis was done based on available data from URA Realis Going by districts, resale homes in District 20 (MacPherson, Potong Pasir, and Braddell) raked in the highest profits on quantum basis, with transactions reaping average gains of more than $825,000 per deal. In terms of annualised gains, resale homes in District 20 enjoyed the highest average annualised profit of 4.5% per deal. Top 10 Resale Condo districts^ in terms of average gross profit* (August 2026)DistrictNo. of transactions**Average Gains ($)Average Annualised Gains (%)#D2044$825,7964.5%D2190$796,3963.3%D1536$777,2323.9%D827$702,2204.0%D1036$689,2452.2%D1651$641,8484.1%D2243$527,2333.7%D2849$517,5273.5%D2372$496,6113.4%D1932$489,5853.9%Source: PropNex Research, URA Realis^Districts with fewer than 10 transactions during the month were excluded from this analysis*Gains are derived from the resale transaction for each unit against the unit's last caveated transaction; the average profit is determined on the profits of all resale transactions in the development which occurred during the month. The profit reflected is gross - it has not accounted for the applicable seller's stamp duties, interest payable, taxes and other relevant divestment costs.#Annualised Gains is the compounded annual rate of return which shows the rate of return over the time period between the point of resale and the property's last caveated transaction, expressed in annual percentage terms. The formula for determining this is simply: [(current resale price) / (purchase price)] time period in years-1Analysis was done based on available data from URA Realis**Resale units with no available last caveated transaction data are excluded from this analysis Analysing individual transactions by gross profit quantum, it was found that the top five gainers from each region ranged from $1.9 million to $3.6 million. The units which chalked up bigger gains were mostly sizeable large format condos that are more than 1,400 sq ft in size, and consisted mostly of older projects built in the 1980s to early 2000s. The respective holding periods for the most profitable resale properties were mostly beyond 15 years - the oldest being a unit held for more than 30 years. Top 5 Resale Condo transactions in August 2026 by gross profit by regionSource: PropNex Research, URA Realis*Gains are derived from the resale transaction for each unit against the unit's last caveated transaction; the average profit is determined on the profits of all resale transactions in the development which occurred during the month. The profit reflected is gross - it has not accounted for the applicable seller's stamp duties, interest payable, taxes and other relevant divestment costs.#Annualised Gains is the compounded annual rate of return which shows the rate of return over the time period between the point of resale and the property's last caveated transaction, expressed in annual percentage terms. The formula for determining this is simply: [(current resale price) / (purchase price)] time period in years-1Analysis was done based on available data from URA Realis**Resale units with no available last caveated transaction data are excluded from this analysis It was found that the overall most profitable transaction and top gainer in the CCR was for a 3rd floor unit at Palm Spring. It was resold for an estimated profit of $3.1 million, reflecting an annualised profit of 5.9%. Based on URA Realis caveat data, the 1,884-sq ft unit was first bought in October 2003 and subsequently resold for $4.25 million in August 2026, with a holding period of nearly 23 years. Palm Spring is a freehold condominium in District 10, completed in 1997 and located along Ewe Boon Road within the established Bukit Timah/Tanglin residential enclave. It is conveniently positioned near Stevens MRT station on the Downtown and Thomson-East Coast lines, with reputable schools including Anglo-Chinese School (Primary), Singapore Chinese Girls' Primary School and Anglo-Chinese School (Barker Road) in the vicinity.The top gainer in the RCR in terms of gross profit was for unit transacted at The Esta, which fetched a gross profit of $2.67 million (annualised profit of 6.2%), based on caveats lodged. The 1,561-sq ft 5th floor unit was sold for $3.79 million, with a holding period of 20 years. The Esta is a freehold condominium in District 15, completed in 2008 and situated along Amber Gardens in the established Katong-Marine Parade enclave. It is conveniently located within walking distance of Tanjong Katong MRT station on the Thomson-East Coast Line, while nearby schools include Tanjong Katong Primary School, Tanjong Katong Secondary School and Tanjong Katong Girls' School.Over in the OCR, the top gainer in August was a 10th floor unit located in The Hillside in District 21. The 2,648-sq ft unit was sold for $5.18 million, achieving an estimated profit of $3.59 million - which reflects an annualised profit of 4.6% over a holding period of 26 years. The Hillside is a freehold condominium in District 21, completed in 2001 and situated along Upper Bukit Timah Road within an established, greenery-rich residential enclave. It is just a short walk from Hume MRT station on the Downtown Line, while nearby schools include Keming Primary School, Lianhua Primary School and CHIJ Our Lady Queen of Peace. The development also benefits from its proximity to Bukit Timah Nature Reserve and Bukit Batok Nature Park, as well as established amenities such as The Rail Mall and HillV2.Amid a still-low interest rate environment and rising new launch prices, condo resellers August stand to benefit as some homebuyers August find themselves priced out of the new launch market and could consider options in the resale segment.
Read More
A New Wave Of Homes Is Reshaping Bright Hill
State land for residential use rarely comes up in this part of the neighbourhood. The last residential land parcel released for tender in Lorong Puntong was in October 2014. Well, the wait has now ended. The government land sales (GLS) tender for the Lorong Puntong/Sin Ming Avenue site attracted seven bids when it closed on 15 September 2026. The top bid of $208.1 million - which translates to a land rate of $1,612 psf per plot ratio (psf ppr) - came from Eco World Development. The plot is expected to yield about 140 new homes and has a site area of about 0.43 hectares, making it the smallest site on the Confirmed List of the first-half 2026 GLS Programme.While the plot may be small, it is big on location attributes.Effortless commute with MRT station close byThe Bright Hill MRT station on the Thomson-East Coast Line (TEL) is a five-minute walk from the site. It provides residents with a seamless commute to key employment hubs and attractions at locations such as Woodlands, Orchard Road, Outram Park, Maxwell, Shenton Way, Marina Bay, and then eastward to Bayshore.With Bright Hill set to become an interchange for the TEL and the upcoming Cross Island Line (CRL), connectivity is expected to improve further as the CRL progressively opens. Phase 1, which runs from Aviation Park to Bright Hill, is targeted for completion in 2030, while Phase 2, comprising Turf City, King Albert Park, Maju, Clementi, West Coast and Jurong Lake District, is slated for completion in 2032. Once both phases are up and running, Bright Hill will become a key interchange providing connections across the northern, southern, eastern and western parts of Singapore, further enhancing its accessibility.Frequent visitors to Johor may also be attracted by the relatively easy commute to the Woodlands North transport hub via the TEL, located just six stations away from Bright Hill. Woodlands North will be the Singapore terminus of the Johor Bahru-Singapore Rapid Transit System (RTS) Link, which will be connected to the existing Woodlands North TEL MRT station. Targeted to commence passenger service in early-2027, the RTS Link will take about five minutes to travel between Woodlands North and Bukit Chagar in Johor Bahru, significantly improving connectivity between Singapore and Malaysia.Opposite popular Ai Tong School Another strength of the site is its proximity to a number of schools. Notably, it is virtually on the doorstep of the popular Ai Tong School, with other primary schools like CHIJ St. Nicholas Girls' School, Ang Mo Kio Primary School, and Catholic High School within a 1-2km radius from the site. Meanwhile, Peirce Secondary School and Mayflower Secondary School are about 25 minutes away by public transport, while Eunoia Junior College is a 15-minute bus ride from the site. Amenities and green spaces Future residents at the upcoming Lorong Puntong project can find commercial amenities at the nearby Thomson Plaza, and Sin Ming Plaza at Upper Thomson about 15 minutes away from the site. More F&B and retail options can also be found slightly further out at AMK Hub, Lentor Modern, Junction 8 at Bishan, and the numerous shopping malls in Orchard Road. A distinctive feature of the site is its proximity to green spaces and parks, such as the Bishan-Ang Mo Kio Park, and Windsor Nature Park, creating plenty of opportunities for residents to explore the extensive forest trails it has to offer. A neighbourhood that is set to get livelier Apart from more private homes being introduced in the area, the Housing and Development Board will also be launching new flats in Sin Ming Street. It was reported in August 2026 that a 1,076-unit project that will include a childcare centre and a supermarket is currently being constructed across the road from Sin Ming Residences, a public housing project that is nearing completion with 984 units. The new flats' launch date has yet to be announced.Together, these new public and private housing developments are expected to contribute to livelier residential environment, with a larger resident population supporting demand for amenities and services in the area.DeveloperEco World Development is a public listed Malaysian real estate developer with an established footprint in Kuala Lumpur, Penang, Iskandar Malaysia and more. Regarded as one of Malaysia's premier property developers, the developer owns over 11,000 acres of land bank across the country. Their portfolio spans across London, Australia and Malaysia and includes residential and commercial buildings, with notable projects including Bukit Bintang City Centre in Kuala Lumpur, Eco Botanic in Johor Bahru, Yarra One in Melbourne, and Embassy Gardens in London.
Read More
Too Rich for a BTO, Too Poor for a Condo: What the New Income Ceilings Mean for You
TL;DR For households that were earning just a little too much for a BTO, the new income ceilings could reopen some doors. But qualifying for a flat does not automatically mean it is affordable, so buyers still need to look beyond the ceiling itself. What changed: The income ceiling for families buying BTO flats has risen from $14,000 to $16,000, while the ceiling for singles aged 35 and above has increased from $7,000 to $8,000. The EC ceiling has also risen from $16,000 to $18,000 for qualifying new projects. Who benefits: Middle-income households that previously crossed the old ceiling may now qualify for BTOs, along with certain housing grants and schemes. This gives some households more options between subsidised housing and the private market. Resale impact: Some buyers who would previously have turned to the resale market may now consider BTO instead. But resale demand is unlikely to disappear, as buyers still value immediate availability, specific locations and housing options that BTO cannot always provide. Timing matters: The next BTO exercise is scheduled for November 2026, with around 7,960 flats across six towns. Those hoping to apply should submit their required HFE documents by 25 September 2026. Eligibility is only the first step: Falling below the income ceiling does not mean you can comfortably afford any flat. Your loan, CPF, cash savings and existing monthly commitments still determine what you can realistically take on. Bottom line: The higher income ceilings give some middle-income households a wider range of housing options, especially those who were previously just above the old limits. But the real question is not just whether you qualify for a BTO. It is whether the flat, financing and timeline still make sense for your household. On 23 August, at his National Day Rally speech, Prime Minister Lawrence Wong announced a change to the public housing income ceiling. This was the first time in seven years. Before this, the income ceiling for BTO flats and Executive Condos (ECs) hadn't moved since 2019.So what does this mean for you? In this article, we will explore: What changed? Why does this matter? Who benefits most? What this means for the resale market? Thinking of Applying for a BTO? Final thoughts What changed?The income ceiling for families buying BTO flats went up from $14,000 to $16,000 a month. For singles aged 35 and above, the ceiling went up from $7,000 to $8,000. And for ECs it went up from $16,000 to $18,000 (this only applies to new units where the land-sale tender closes on or after 24 Aug 2026; balance units and earlier-tendered projects stay at $16,000).On top of that, several housing schemes will see their income ceilings raised too, including the Parenthood Provisional Housing Scheme, Fresh Start Housing Scheme, Step-Up CPF Housing Grant, Lease Buyback Scheme, Silver Housing Bonus and Community Care Apartments.For extended families (three generations living under one household), the combined income ceiling is now $24,000. However, each family nucleus within that household still has to stay within the individual $16,000 ceiling.Why does this matter?Well, income ceiling is one of the main factors that decides who can apply for a BTO flat, who qualifies for Plus and Prime flats, who can buy an EC, and who is eligible for CPF grants and HDB loans.(Note: Standard resale flats do not have an income ceiling for the purchase itself, but income ceilings apply to CPF Housing Grants and HDB loans.)Raising the income ceiling means more households who were just above the old ceiling may now find themselves within the qualifying range. Enjoying our insights so far? Stay updated with the latest property trends, expert analysis, and market perspectives from PropNex. Join our mailing list Who benefits most?For the longest time, the sandwich class had the least support. They were too rich to qualify for various subsidies, but not rich enough to buy into the private market.So with this income ceiling revision, they are perhaps the group with the most to gain.Let me paint you a picture.A couple started house-hunting a few years ago. One was earning $6,500 a month, the other $5,500. Together, that puts them at $12,000, which was comfortably below the $14,000 ceiling at the time.So they started planning for a BTO.As they were saving up for a downpayment, one got promoted and received a $1,000 pay raise. The other moved to a new job and started earning $1,200 more. After two years and some annual appraisals, suddenly they were earning about $14,500 a month.Nothing about their housing situation had really changed. They were still looking at an HDB flat. They were not suddenly shopping for a condo just because their salaries had gone up.But that extra $2,500 a month had pushed them over the income ceiling, which means some of the HDB support they had previously been eligible for was no longer available to them.So, they resorted to the resale market, even though they might not have had enough cash or CPF to comfortably make that jump. Earning more had made it more difficult for them to be homeowners. Ironic, isn't it?But now that the income ceiling is raised to $16,000, that couple earning $14,500 would once again fall within the income range for a BTO.It doesn't necessarily make housing cheaper, but it gives middle income households like them more breathing room.What this means for the resale marketThe question now is: if more households can qualify for BTO, does that take demand and prices out of the resale market?It's possible, but probably not drastically.The resale market has already had a bit of a breather. Prices dipped 0.3% in Q2 2026, after falling for the first time in almost seven years in Q1.At the same time, the new $16,000 ceiling now covers households just under the 70th percentile of resident employed households, based on 2025 SingStat data. So yes, there's a sizeable group of buyers who now have the option of going for a subsidised new flat instead of resale.We can expect some of these buyers to shift away from larger, more expensive resale flats, especially if they can get a bigger or better-positioned BTO unit at a lower price. On top of that, demand for well-located BTO projects will likely strengthen.We also can't forget that we are experiencing a surge in resale supply, with around 13,500 flats are reaching their MOP in 2026, and another 34,500 flats expected to reach MOP across 2027 and 2028. At the same time, HDB maintains a steady BTO supply and plans to launch around 19,600 flats in 2026 alone.All that is to say that if resale prices do soften over the next few years, it won't be solely because the income ceiling revision shifted some demand towards BTO.For one thing, BTO and resale buyers aren't always looking for the same thing. If you need to move in soon, want to live in a particular neighbourhood, or simply don't want to wait years for a new flat, resale is still the more practical option.Resale also caters to buyers who aren't eligible for BTO in the first place, including permanent residents (PRs) and singles looking for something larger than a 2-room Flexi.Thinking of Applying for a BTO?You should take note that the next BTO exercise will take place in November 2026. However, all the required HFE documents must be submitted by 25 September 2026.The November exercise is expected to offer about 7,960 flats across Bedok, Geylang, Sembawang, Tengah, Toa Payoh and Yishun.So if you were previously just above the income ceiling and thought, "Well, BTO is off the table for me," this might be a good time to check again.Final thoughtsFor years, the middle class has felt that the income ceilings were getting a little outdated.A lot has changed since the last revision in 2019. Salaries have gone up and property prices have moved. Yet, a pay raise could mean losing access to housing options.The new ceilings remove one barrier for many households. But clearing the income ceiling is only the first step. What you can actually afford will still depend on other factors such as your loan, CPF, cash and monthly commitments. Views expressed in this article belong to the writer(s) and do not reflect PropNex's position. No part of this content may be reproduced, distributed, transmitted, displayed, published, or broadcast in any form or by any means without the prior written consent of PropNex. For permission to use, reproduce, or distribute any content, please contact the Corporate Communications department. PropNex reserves the right to modify or update this disclaimer at any time without prior notice.
Read MoreQuick insights you can apply immediately-from market indicators to financing perspectives.
Featured In-Person Learning Opportunities
Join our signature CES sessions to understand market trends, upgrading paths, and common property pitfalls — a helpful starting point before exploring deeper topics.


What People Say
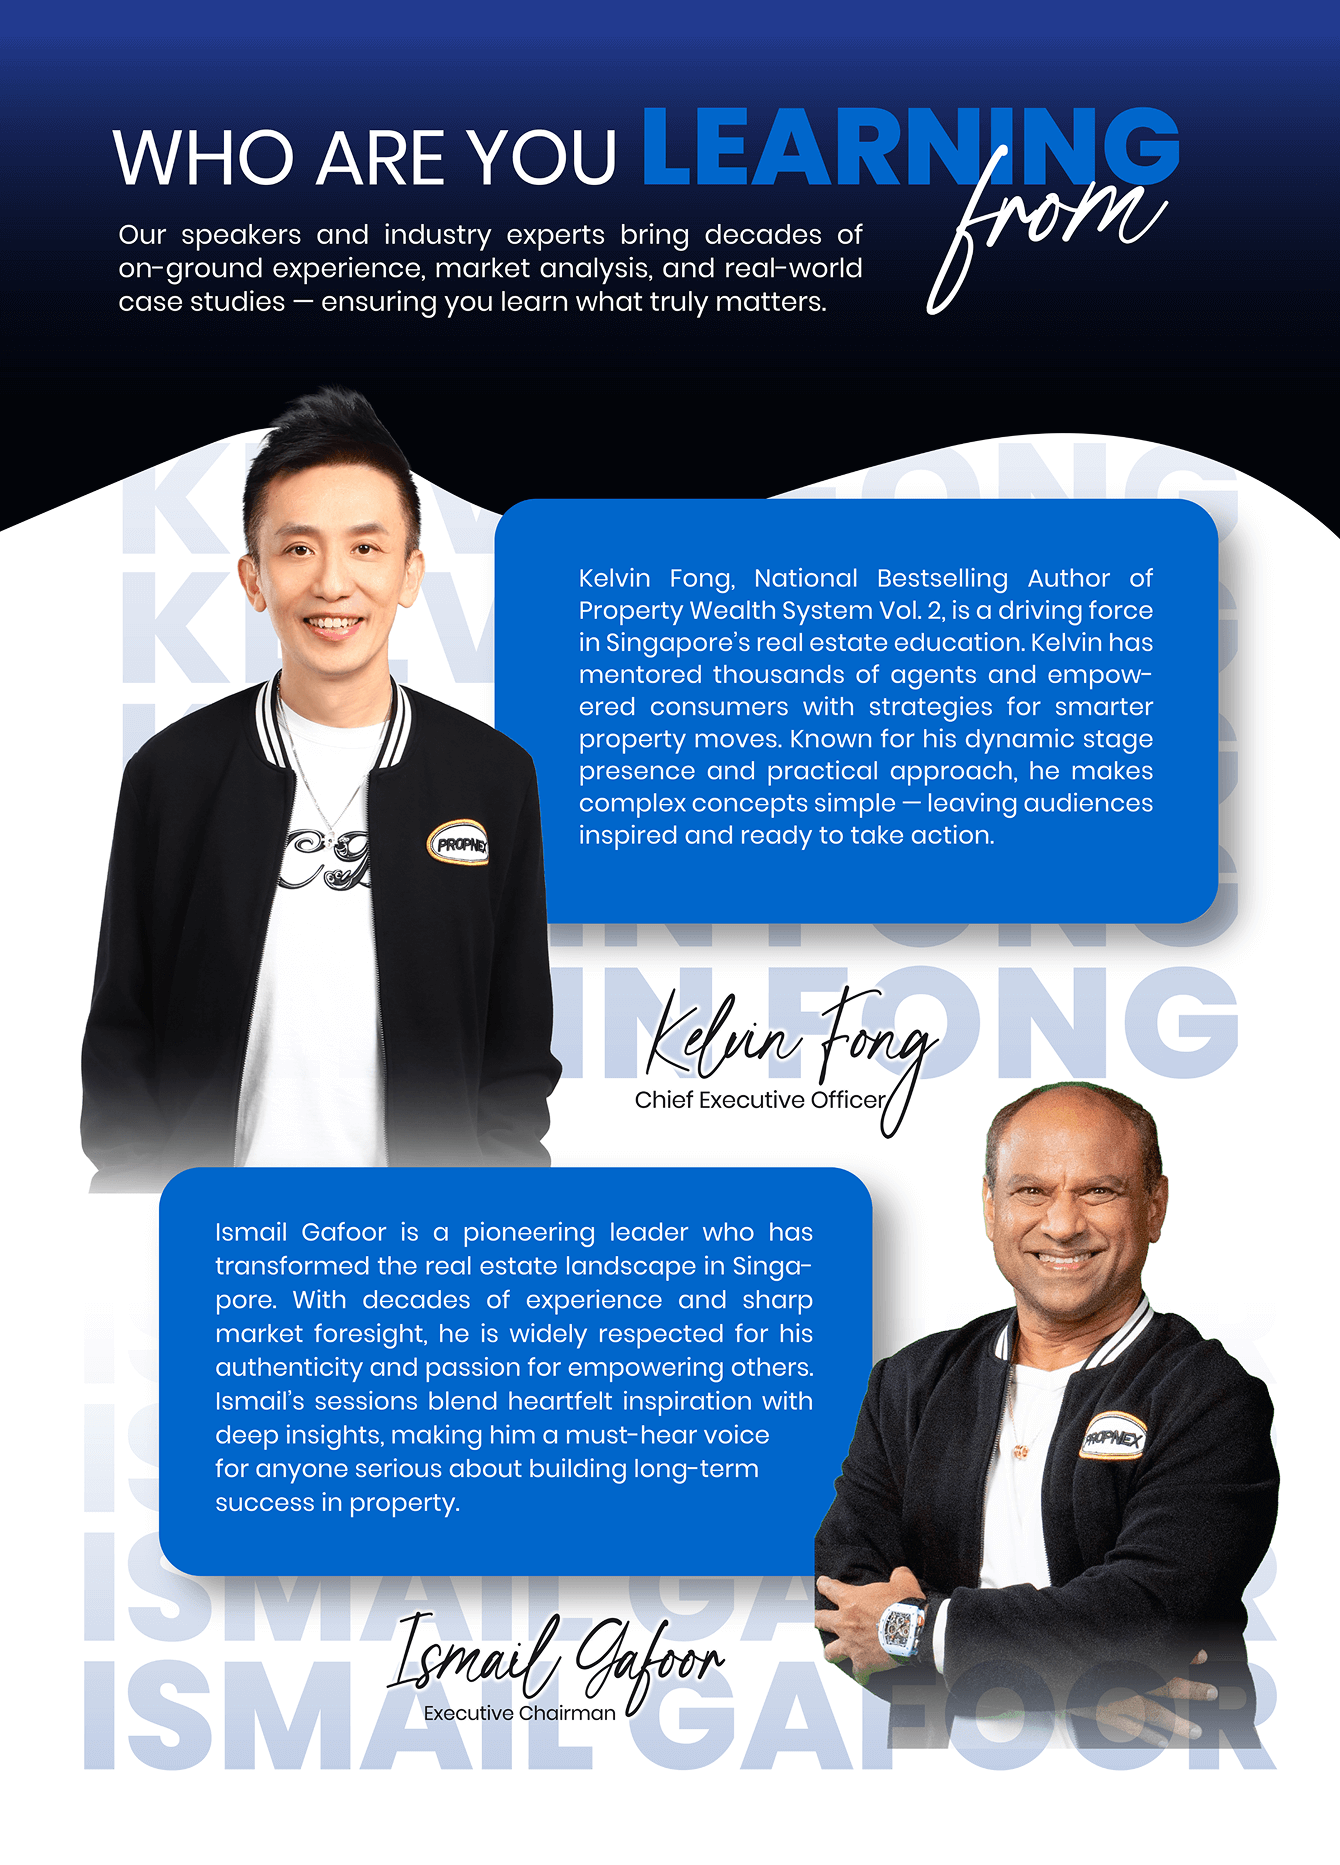
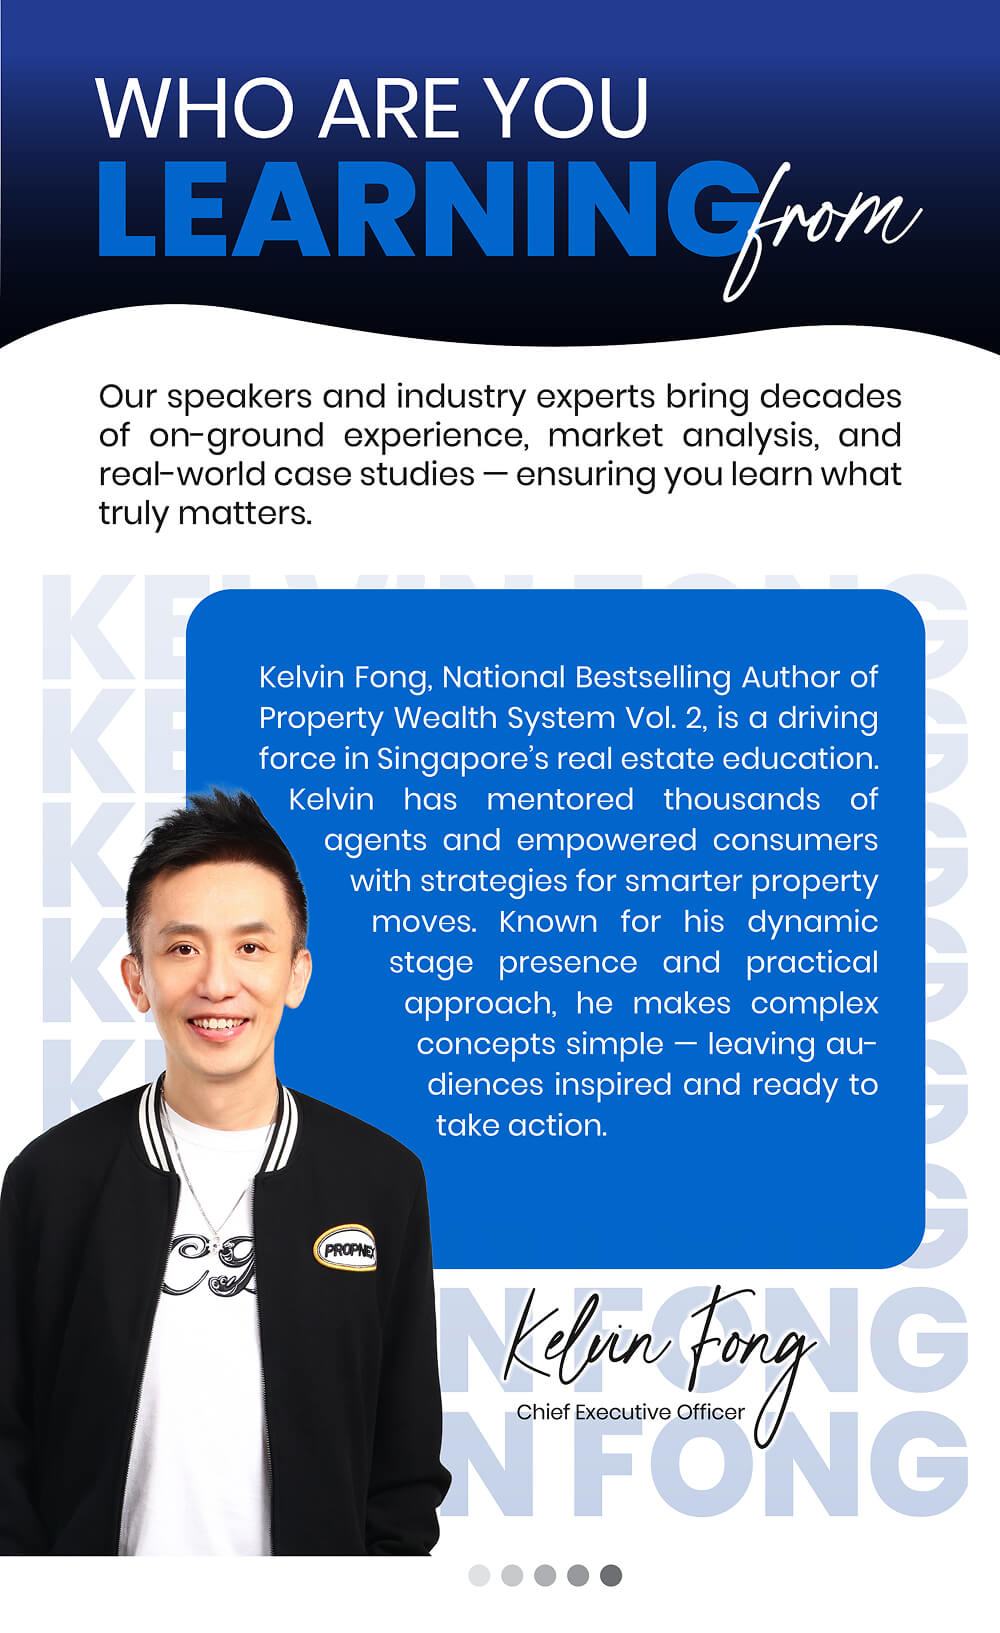
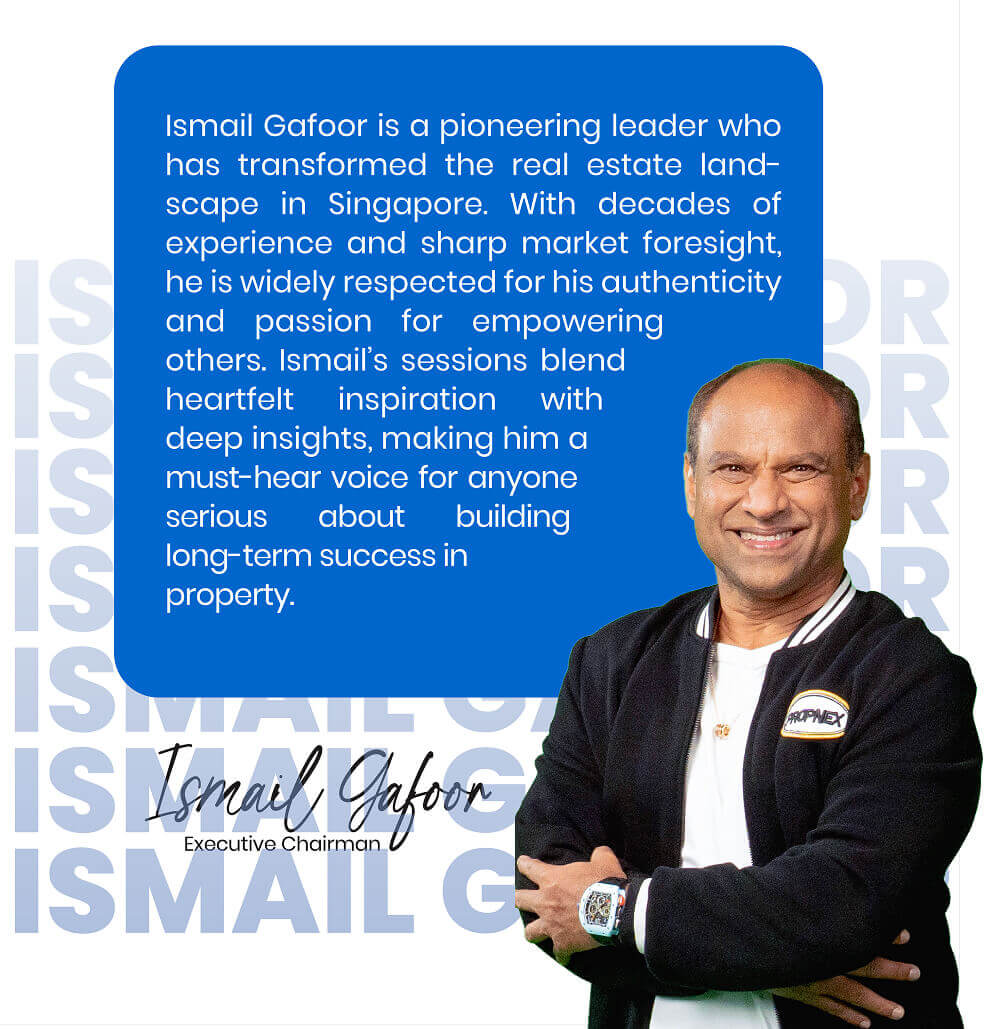
Our speakers bring decades of real estate experience, backed by market research and real case studies. Hear directly from experts who have guided thousands of consumers and investors.
01 Are these seminars free to attend?
02 Who should attend?
03Do I need prior property knowledge?
04 Can I ask questions during the seminar?
05 Is this Learning Hub only about seminars?
Frequently
Asked Questions
Deep-Dive Learning Pathways
Beyond introductory concepts, our PWS Masterclass offers a structured, hands-on approach for homeowners and investors ready to plan long-term wealth strategies.
For those who want to go deeper, the Property Wealth System (PWS) Masterclass is a 2-day immersive workshop where you’ll:
Apply the same frameworks you learned at CES in a hands-on way
Learn to calculate and assess your own property portfolio and “property health”
Build a clear, step-by-step action plan for long-term wealth creation through property
Think of CES as your starting point to understand the market — and PWS as your roadmap to take decisive action with confidence.